

Annuity mortgage (annuïteitenhypotheek): fixed monthly payments, fully repaid
The same amount every month. No surprises, no complicated calculations. That is the biggest advantage of an annuity mortgage (annuïteitenhypotheek). You know exactly where you stand for as long as your interest rate is fixed. Meanwhile, you repay a little each month, so your debt gradually decreases and after thirty years you are completely mortgage-free.
The annuity mortgage is the most popular mortgage type in the Netherlands. And for good reason. But does it suit your situation? That depends on your income, your plans and what you want to keep net each month. We are happy to work that out with you.
How an annuity mortgage works
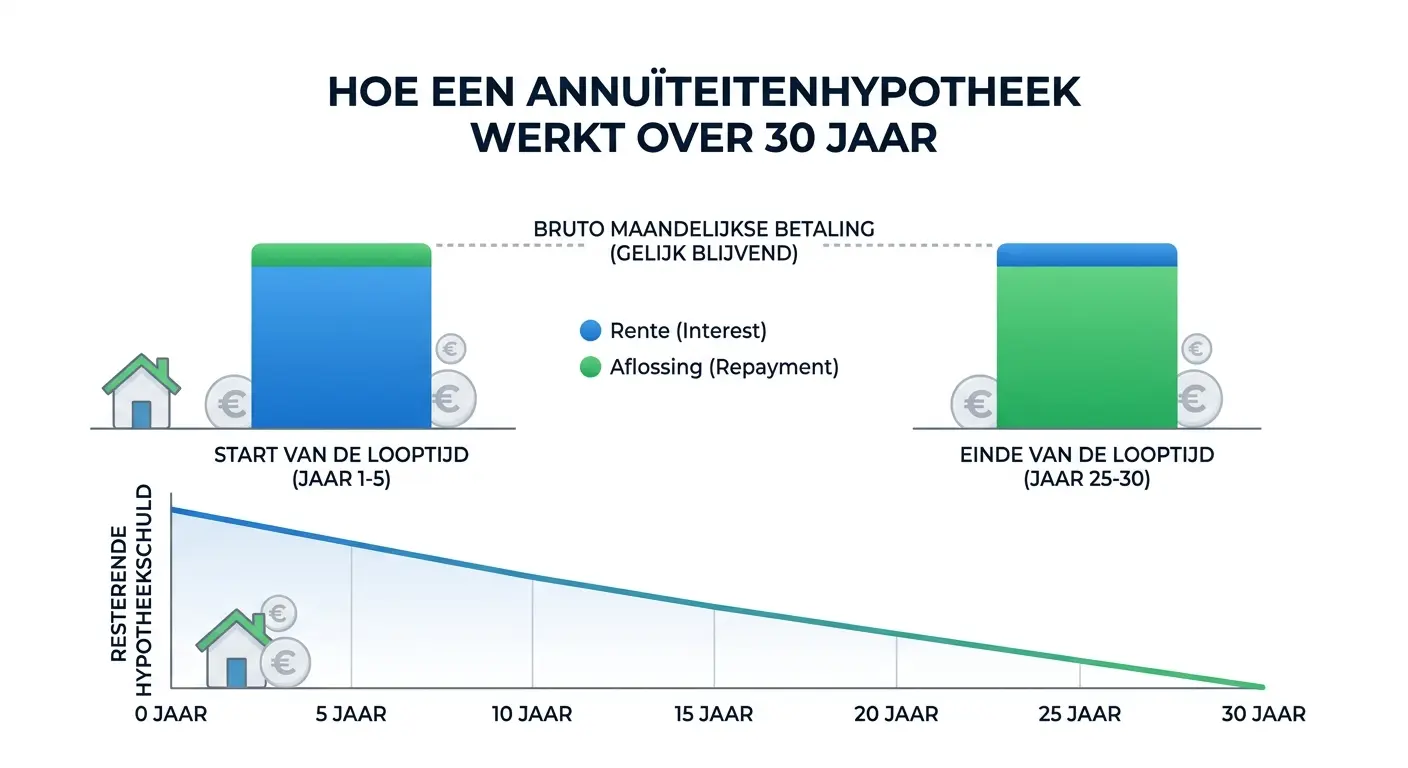
Every month you pay a fixed gross amount — the annuity. This amount consists of two parts: interest and repayment. At the start of the term you pay mainly interest and very little repayment. As the years pass, that ratio shifts. Your debt decreases, so you pay less interest and more repayment.
The gross amount stays the same. However, your net payment rises slightly over time, because you pay less interest and therefore have less to deduct from your taxes. That is the one downside of the annuity mortgage. The good news: after thirty years your mortgage is fully repaid.
- Fixed gross payment: you know exactly what you pay each month for as long as your interest rate is fixed.
- Mortgage interest deduction (hypotheekrenteaftrek): the interest you pay is tax-deductible in box 1 (maximum 37.5% in 2026).
- Full repayment: at the end of the term you are completely debt-free.
- Growing home equity: because you repay every month, your equity (overwaarde) grows steadily.
Annuity mortgage or linear mortgage (lineaire hypotheek)?
This is the question almost everyone asks. Both mortgage types repay in full and both qualify for mortgage interest deduction. The difference lies in the monthly payments.
Annuity mortgage
- Fixed gross payment, rising net payment
- Lower net payment at the start than a linear mortgage
- More tax benefit in the early years
- Ideal if you need maximum borrowing capacity now
- Most chosen mortgage type in the Netherlands
Linear mortgage
- Fixed repayment amount, decreasing monthly payment
- Higher net payment at the start than an annuity mortgage
- Debt decreases faster, so less total interest paid
- Ideal if you want more financial breathing room later
- Attractive for move-up buyers with existing home equity
Which option works out best for you depends on your income, tax bracket and future plans. We are happy to calculate it together.
Mortgage interest deduction (hypotheekrenteaftrek) and the annuity mortgage
An annuity mortgage qualifies for mortgage interest deduction (hypotheekrenteaftrek). This means you can deduct the interest you pay from your taxable income in box 1. In 2026 the maximum deduction rate is 37.5%.
Because you pay less interest over time as your debt decreases, your tax benefit also reduces gradually. Your net monthly payment therefore rises slightly over the term. That may sound like a drawback, but at the same time your debt is falling. In the end you are completely debt-free.
Important to know: mortgage interest deduction only applies to mortgages that are fully repaid during the term. The annuity mortgage meets that requirement exactly. Did you take out a different mortgage type before 2013? Different rules may apply. We are happy to look at what works best in your specific situation.
Your annuity mortgage in 5 steps
- Free introduction
We get to know your situation: income, housing wishes and future plans. No obligations. - Mortgage calculation
We calculate your maximum mortgage and your expected monthly payments, both gross and net. - Choosing your mortgage type
We explain the pros and cons of an annuity versus a linear mortgage for your specific situation. - Requesting a quote
We request a quote from the lender that fits you best — not the one with the highest commission. - Completing your mortgage
We handle everything from application to the notary. You sign and enjoy financial peace of mind.
Frequently asked questions about the annuity mortgage
What is an annuity mortgage (annuïteitenhypotheek)?
An annuity mortgage (annuïteitenhypotheek) is a mortgage type where you pay the same gross amount every month, combining interest and repayment. At the start you pay mainly interest and little repayment. As you repay more, that ratio shifts: you pay less and less interest and more and more repayment. After the full term of thirty years, your mortgage is completely paid off.
What are the disadvantages of an annuity mortgage?
The main drawback is that your net monthly payment rises slightly over time. Because you pay less interest, you have less to deduct from your taxes, so you pay a little more net. At the same time your debt is falling, so your home equity grows. Compared to a linear mortgage, you also pay slightly more total interest over the full term, because your debt decreases more slowly.
Is an annuity mortgage better than a linear mortgage?
It depends on your personal situation. An annuity mortgage has a lower net payment at the start, which is useful if you need maximum borrowing capacity right now. A linear mortgage is more cost-efficient over the long term because your debt decreases faster and you pay less total interest. Want to know which works best for you? We work it out together in a personal advice session.
Can I adjust or refinance my annuity mortgage during the term?
Yes, that is possible. Most lenders allow you to make penalty-free extra repayments each year, typically 10 to 20% of the original loan amount. You can also refinance (oversluiten) your mortgage if it becomes financially attractive — for example, if interest rates have dropped significantly. Bear in mind that early repayment charges may apply. We are happy to calculate whether refinancing makes sense in your situation.
Does an annuity mortgage qualify for mortgage interest deduction?
Yes. The annuity mortgage fully qualifies for mortgage interest deduction (hypotheekrenteaftrek) because the loan is fully repaid during the term. You may deduct the interest you pay from your taxable income in box 1. In 2026 the maximum deduction rate is 37.5%. The deductible amount decreases over the years as you pay less interest.
What does mortgage advice at Libero Financieel cost?
We work with fixed, transparent advisory fees that are clear upfront — you will never pay more than agreed. View our current fees on the rates page or simply ask during your free introduction.
100% independent mortgage advice
Libero Financieel does not choose the lender with the highest commission — we choose the mortgage that fits you best. That is our starting point in every conversation, whether you are a first-time buyer, a move-up buyer or self-employed.
A free introduction takes about half an hour. Afterwards you will know exactly what your options are.